Investing in property abroad offers a compelling way to diversify a financial portfolio, secure a holiday home, or generate passive income in a new currency. With global travel normalising and remote work policies becoming permanent for many professionals, cross-border real estate transactions are surging.
Furthermore, a physical asset located in a growing overseas market acts as a robust hedge against domestic inflation. In 2024, Thailand registered 14,573 condominium transfers to foreign buyers, reflecting steady offshore demand accounting for tens of billions of baht annually. However, acquiring a physical asset in a foreign jurisdiction requires careful planning and a thorough understanding of local regulations.
Assessing the Regional Economic Outlook
Before committing capital, astute investors should analyse macroeconomic indicators to ensure their target market is stable. The Asia-Pacific region, in particular, is drawing significant attention from offshore buyers seeking a blend of capital appreciation and lifestyle benefits. Evaluating employment rates, infrastructure development plans, and foreign direct investment trends can provide a clearer picture of future property valuations. An area with upcoming transport links or new commercial hubs often promises superior capital appreciation.
According to CBRE’s recent Asia Pacific real estate market outlook, regional GDP growth is forecasted to reach 4.1 percent in 2025, and international visitor arrivals are expected to fully recover to 700 million, supporting robust real estate and hospitality fundamentals in the region. This impressive regional stability provides an excellent foundation for those looking to acquire residential assets in popular hubs, ensuring that property values remain supported by a strong economic backbone.
Understanding Local Ownership Laws
Every country dictates strict rules regarding foreign land ownership. In many Southeast Asian nations, direct freehold ownership of land is restricted for non-citizens, making condominiums a legally straightforward alternative. Navigating these legal frameworks effectively often requires retaining a qualified local solicitor to conduct comprehensive due diligence prior to signing any contracts.
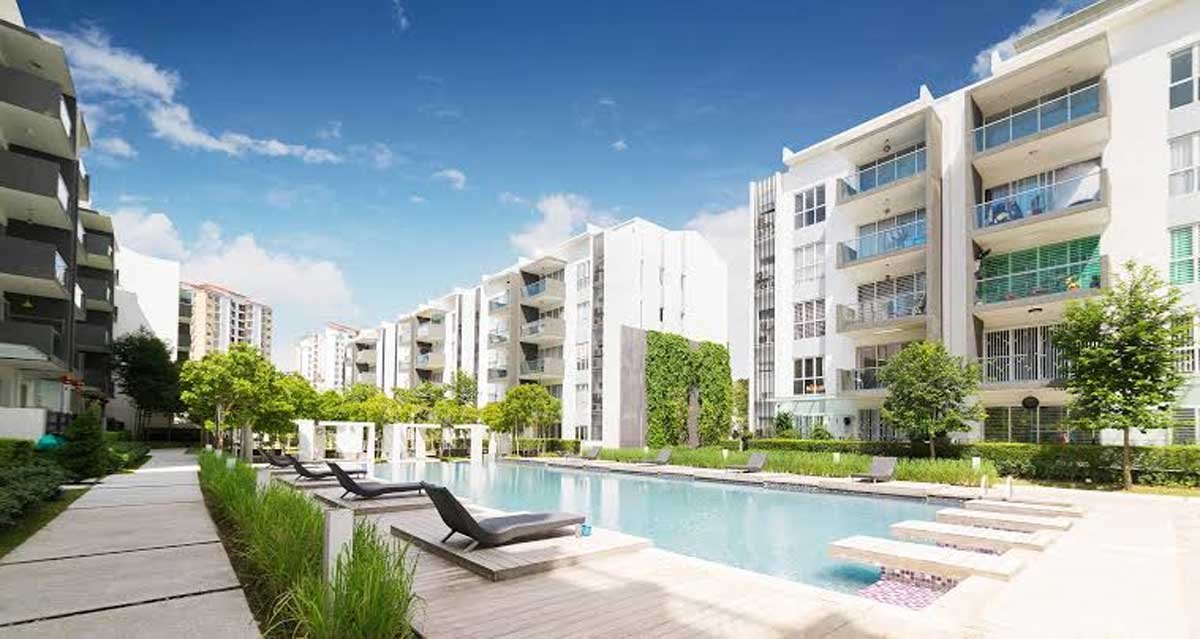
For instance, when browsing a Thailand condo for sale, buyers will find that under Section 19 bis of the Thai Condominium Act B.E. 2522, foreign nationals are legally permitted to hold full freehold ownership of condominium units in their own name. However, foreign freehold ownership in any single registered condominium building is strictly capped at 49 percent of the development’s total saleable floor area. Units in developments that have already reached their maximum foreign ownership limits can only be acquired by foreigners via leasehold structures.
To legally register freehold ownership at the local Land Office, foreign purchasers must remit their purchase funds from overseas in a foreign currency and obtain a Foreign Exchange Transaction form from a receiving Thai bank. Once all paperwork is cleared, buyers receive an Or Chor 2 deed, the official legal document representing freehold ownership of a condo unit.
Maximising Your Investment Yield
Many buyers purchase overseas condominiums with the dual intention of personal use and rental income. Strong tenant demand is crucial for the latter. The widespread issuance of the Destination Thailand Visa has brought a steady pipeline of remote workers seeking mid-term leases of one to six months, directly expanding the tenant pool. Selecting the right property management agency can make a significant difference in maintaining high occupancy and ensuring the physical upkeep of the unit.
As of the third quarter of 2026, Thailand’s average gross rental yield stood at a healthy 6.54 percent. Condominiums in Bangkok typically feature highly stable annual occupancy rates exceeding 85 percent and command gross rental yields of 5.2 to 6.2 percent. Meanwhile, properties in tourist-heavy regions like Phuket can offer yields ranging up to 12 percent depending on the asset class and exact location.
If you plan to lease out your asset while you are away, understanding property management logistics is vital. It is highly recommended to review the essential steps for converting your primary residence into a rental property to understand how to handle operational management, evaluate financial margins, and mitigate insurance risks.
Budgeting for Taxes and Closing Costs
The sticker price of a property is rarely the final amount you will pay. Closing costs and ongoing taxes vary dramatically from one jurisdiction to another, and failing to budget for them can severely impact your expected returns. In Thailand, foreign buyers should budget for the following standard expenses:
- Transfer Fees: Property transfers generally incur a standard 2 percent fee based on the government-appraised cadastral value, conventionally split equally between the buyer and the seller.
- Specific Business Tax: A 3.3 percent tax is levied on property sales if the seller has owned the unit for less than five years.
- Stamp Duty: If the seller has held the property for more than five years, a lower 0.5 percent stamp duty applies instead of the Specific Business Tax.
- Income Tax: Foreign buyers who intend to generate rental income are liable for personal income tax on those earnings, which must be declared to the Thai Revenue Department.
- Property Taxes: Annual property taxes are notably low, with investment properties held by individuals generally taxed between 0.02 percent and 0.30 percent of the government-appraised value.
Purchasing a condominium overseas can be a highly rewarding endeavour for those willing to do their research. By understanding the regional economic outlook, navigating local ownership laws, and carefully budgeting for taxes, investors can secure a profitable real estate asset that delivers value for years to come. By taking a systematic approach to evaluating overseas properties, international buyers can minimise their risks and establish a sustainable, income-generating portfolio.